
Sell
Premium exits are not negotiated. They are prepared.
Sell-side M&A for founder-led businesses
Selling your business with FNDRS starts with the Go-To-Market Analysis, $10,000, flat, credited in full against the fee for the sale, then runs in four phases: prepare, market, select, and close. Scott Stepanik leads every sale, for founder-led businesses of typically $1 million to $25 million of adjusted EBITDA.
Before you sell, hear it from the founders who worked with FNDRS.46 founders on film
Welcome
Welcome to M&A at FNDRS
How a FNDRS sale runs, from the first conversation to funds flow, from the people who run it.
The asymmetry
You will sell a business once
The people across the table buy companies for a living. They have a deal team, a diligence playbook, a financing model, and a view of what your business is worth that they formed before the first call. Most founders arrive with a tax return and a number a friend mentioned at dinner.
That gap has a price. It shows up as a lower multiple, as add-backs that get disallowed, as an earn-out you did not want, as a working capital adjustment nobody explained, and as a price reduction in the last week of diligence when you are too tired to walk away.
Our job is to close that gap before it costs you.
The six pillars
Six things every buyer measures
The 36 elements of the FNDRS Elements™ framework roll up into six pillars, each scored from zero to one hundred.
What we do
Prepare, position, process, protect
Four kinds of work, one team. The order is the order a sale happens in.
Prepare
We rebuild your financials the way a buyer's accountants will: restated income statement, adjusted EBITDA, proof of cash, working capital. We find the issues first: the yellow and red flags a buyer would raise.
Position
We decide, with evidence, which category buyers should place you in and where you belong in its valuation range. Then we build the CIM and the narrative to support it.
Process
We build the buyer universe, run outreach under NDA, manage management meetings, and bring multiple qualified parties to the table at the same time. Competition is what turns interest into price.
Protect
From LOI to close, we negotiate structure, manage diligence, and coordinate your attorney and tax advisors. The goal is simple: the deal you signed is the deal that closes.
Why founders choose us
We bring an institutional discipline to every sale: a rigorous process that puts several buyers in competition at once, and a CIM and offering materials written to the standard those buyers expect. We take each company to the right buyers through our own buyer network and database and our team's relationships, not a subscription database alone, and the team includes a CFA charterholder, which matters most in due diligence and the buyer's Quality of Earnings review.
Know your three numbers
Most founders are missing at least two of these
The distance between them tells you whether to sell now, build first, or change the structure. We help you find the second and third. FNDRS helps you plan the first with outside experts.
The number you need
What the next chapter actually costs, after tax, for the rest of your life.
The number the market will pay
Not a rule of thumb. A range, built from your adjusted EBITDA and how buyers will see your risk.
The number you keep
Enterprise value minus debt, fees, working capital adjustments, deferred and contingent consideration, and tax.
How every engagement starts
How does a sale with FNDRS start?
Every sale starts with the Go-To-Market Analysis, $10,000, flat, credited in full against the fee for the sale: before anyone talks to a buyer, we build the file a buyer would build on you. It delivers the deal workbook: your adjusted EBITDA with every add-back tested, your position in the valuation range, the issues a buyer would raise, and three paths side by side, all cash, rolled equity, or keep growing, with the total proceeds of each after five years.
You finish knowing where you are, where you could be, and which exit options are open to you. Whether you go to market next month or in three years is your call.
The deal workbook
Adjusted EBITDA, with every add-back tested and documented.
Who we serve
What size of business does FNDRS sell?
Founder-led businesses of typically $1 million to $25 million of adjusted EBITDA, where the founder is still central and a sale will be the largest financial event of their life.
Sector experience
- Home and exterior services
- Roofing and solar
- Commercial and specialty contracting
- Precision manufacturing
- Industrial distribution and recycling
- Packaging
- Healthcare services and physician practices
- Medical devices
- Consumer and direct-to-consumer brands
- Business services and software
- Insurance and wealth distribution
- Specialty retail and dealerships
- Agritourism and hospitality
Situations we see most
- A founder three years from the exit they want, asking what to fix first.
- A founder with a number in mind who may reach it in two steps: a first sale now, with equity rolled for a second bite later.
- An unsolicited approach from a private equity firm or a competitor.
- A business that has outgrown its category and is being valued like what it used to be.
- Multiple legal entities, shared costs, and related-party leases that need to become one clear story.
- Owner-held real estate alongside the operating business.
- A strong year, or a weak one, that makes normal earnings hard to define.
- Partners with different timelines.
- A tax or holding-period date that fixes the calendar.
The deal team
Led by Scott Stepanik, from the first conversation to the close
Scott Stepanik leads every FNDRS sale, from the first read of the numbers to the day the money moves, with the deal team alongside and the FNDRS founders, who have built companies of their own, behind it.
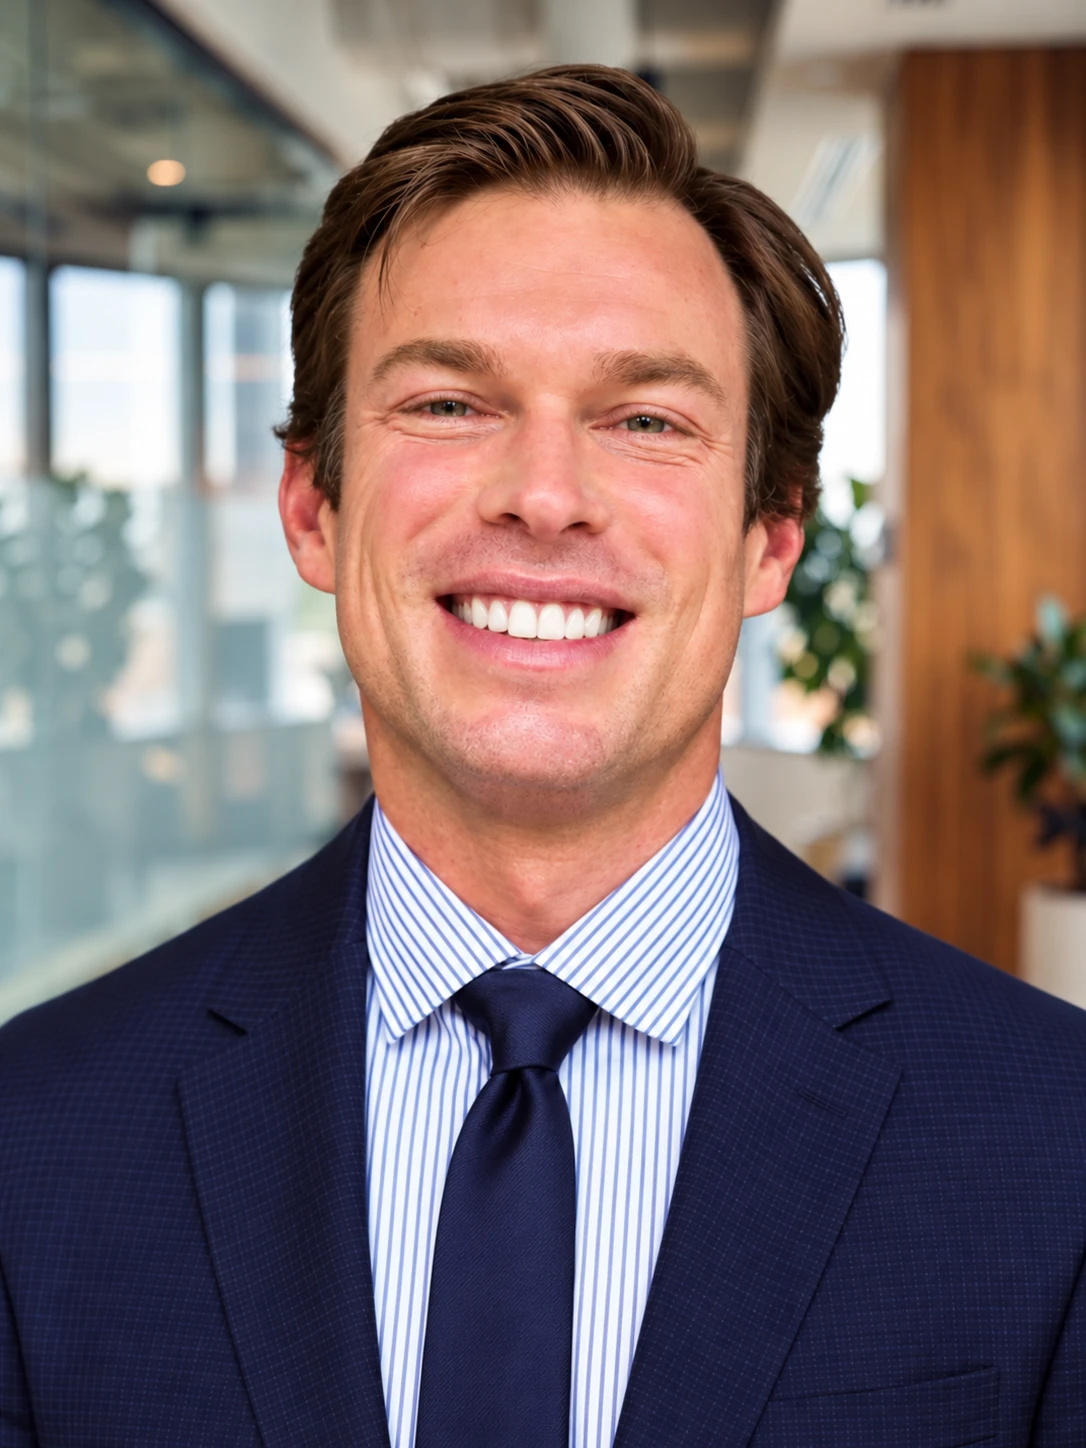
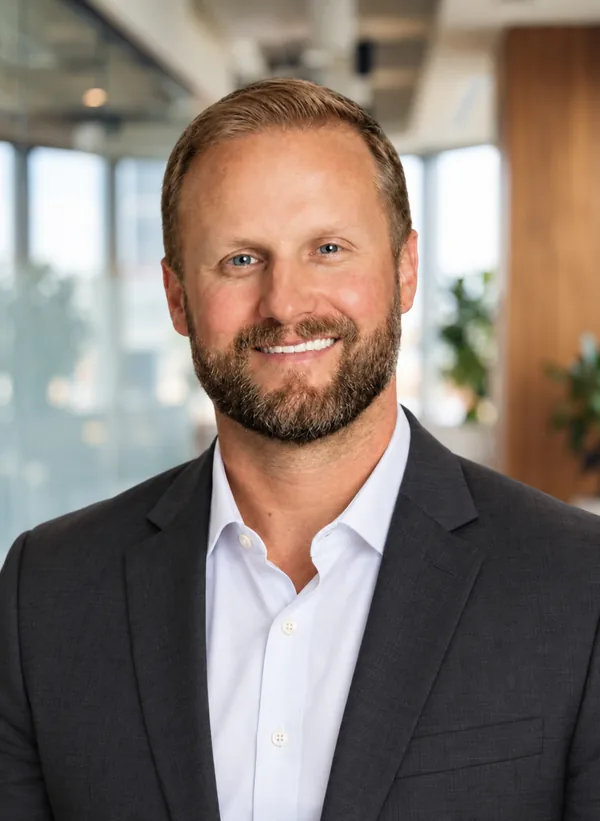
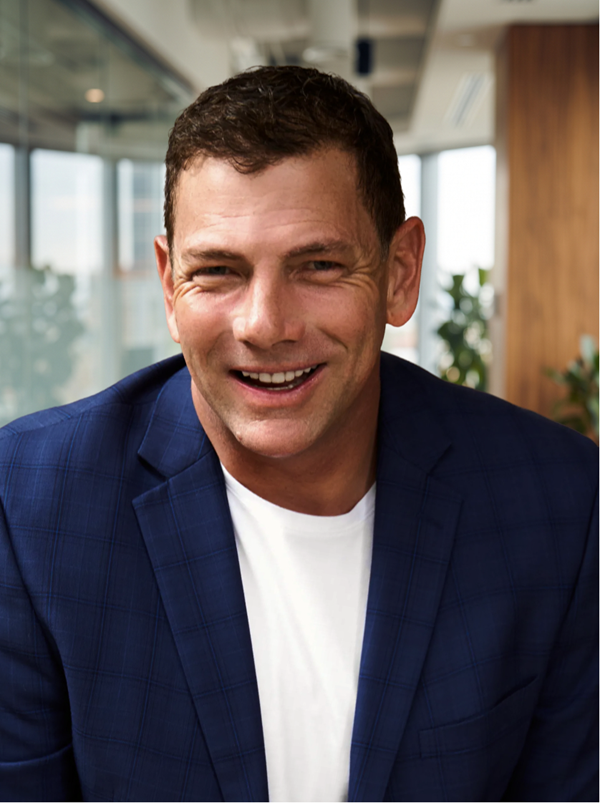 Behind the team: Nick Long and Troy Hoffman, the FNDRS founders, who have built companies of their own.
The FNDRS Exit Playbook
The frameworks we use with founders, published in full
How buyers set multiples. Why add-backs fail. What an LOI is really saying. When to roll equity. Read them before you talk to anyone, including us.
The FNDRS Podcast · Episode 5
The $500K exit lesson
Co-founders Nick Long and Troy Hoffman on what it means to build, scale, and exit a business, and why a cohesive ecosystem beats siloed teams. Troy on the years and money he spent on trial and error before FNDRS, insurance as risk protection, and lessons from the live event’s speakers.
Nick LongHost, CEO and co-founder of FNDRS
29:58Element by element
Hear the elements explained
FNDRS Faculty explain each element of the FNDRS Elements framework: what it is, what it means to a buyer, and where an owner starts. Choose a tile to watch it here: 18 of the 36 have a session of their own so far, and the rest play their part of their family's film.
Troy HoffmanTime
A sale usually takes seven to twelve months from signing to the wire, for a company that is ready. It runs in four phases, prepare, market, select, and close, after the Go-To-Market Analysis. How ready and how complex the company is, the buyers and their lenders, and the lawyers on both sides set each sale's own calendar, which we agree with you at kickoff. Every time given here is an estimate drawn from past engagements, not a commitment.
No. A valuation is an opinion of value on a date. The GTMA is a picture of what a buyer would see, including the adjustments they will make, the issues they will raise, and how different deal structures affect your total proceeds. It is designed for decision-making, not for a report.
Yes: our advisory model is built so that we can afford to say not yet. Many founders who complete a Go-To-Market Analysis spend the time it takes moving up the range before they go to market.
Only the people you agree to, because nothing that identifies the company reaches a buyer before an NDA. Buyers first receive a blind teaser with no identifying details, and anyone who wants more signs a non-disclosure agreement before receiving the CIM. We control who is contacted, in what order, and what they receive, and competitors and customers can be excluded at your direction. Your employees and customers learn about the sale when you decide they should.
We will review it with you. Often the best use of an unsolicited offer is as a floor for a competitive process. Sometimes it is the right deal, and the work is negotiating the terms before exclusivity.
It depends on the buyer and the structure. A strategic buyer with existing management may need three to twelve months of transition. A financial buyer buying a platform may want you for longer, sometimes with a continued equity stake. Your post-close role is one of the terms we negotiate.
Every engagement begins the same way: a confidential conversation about objectives, timing, and options
No pitch. No obligation. If the honest answer is not yet, we will tell you, and tell you what to work on.